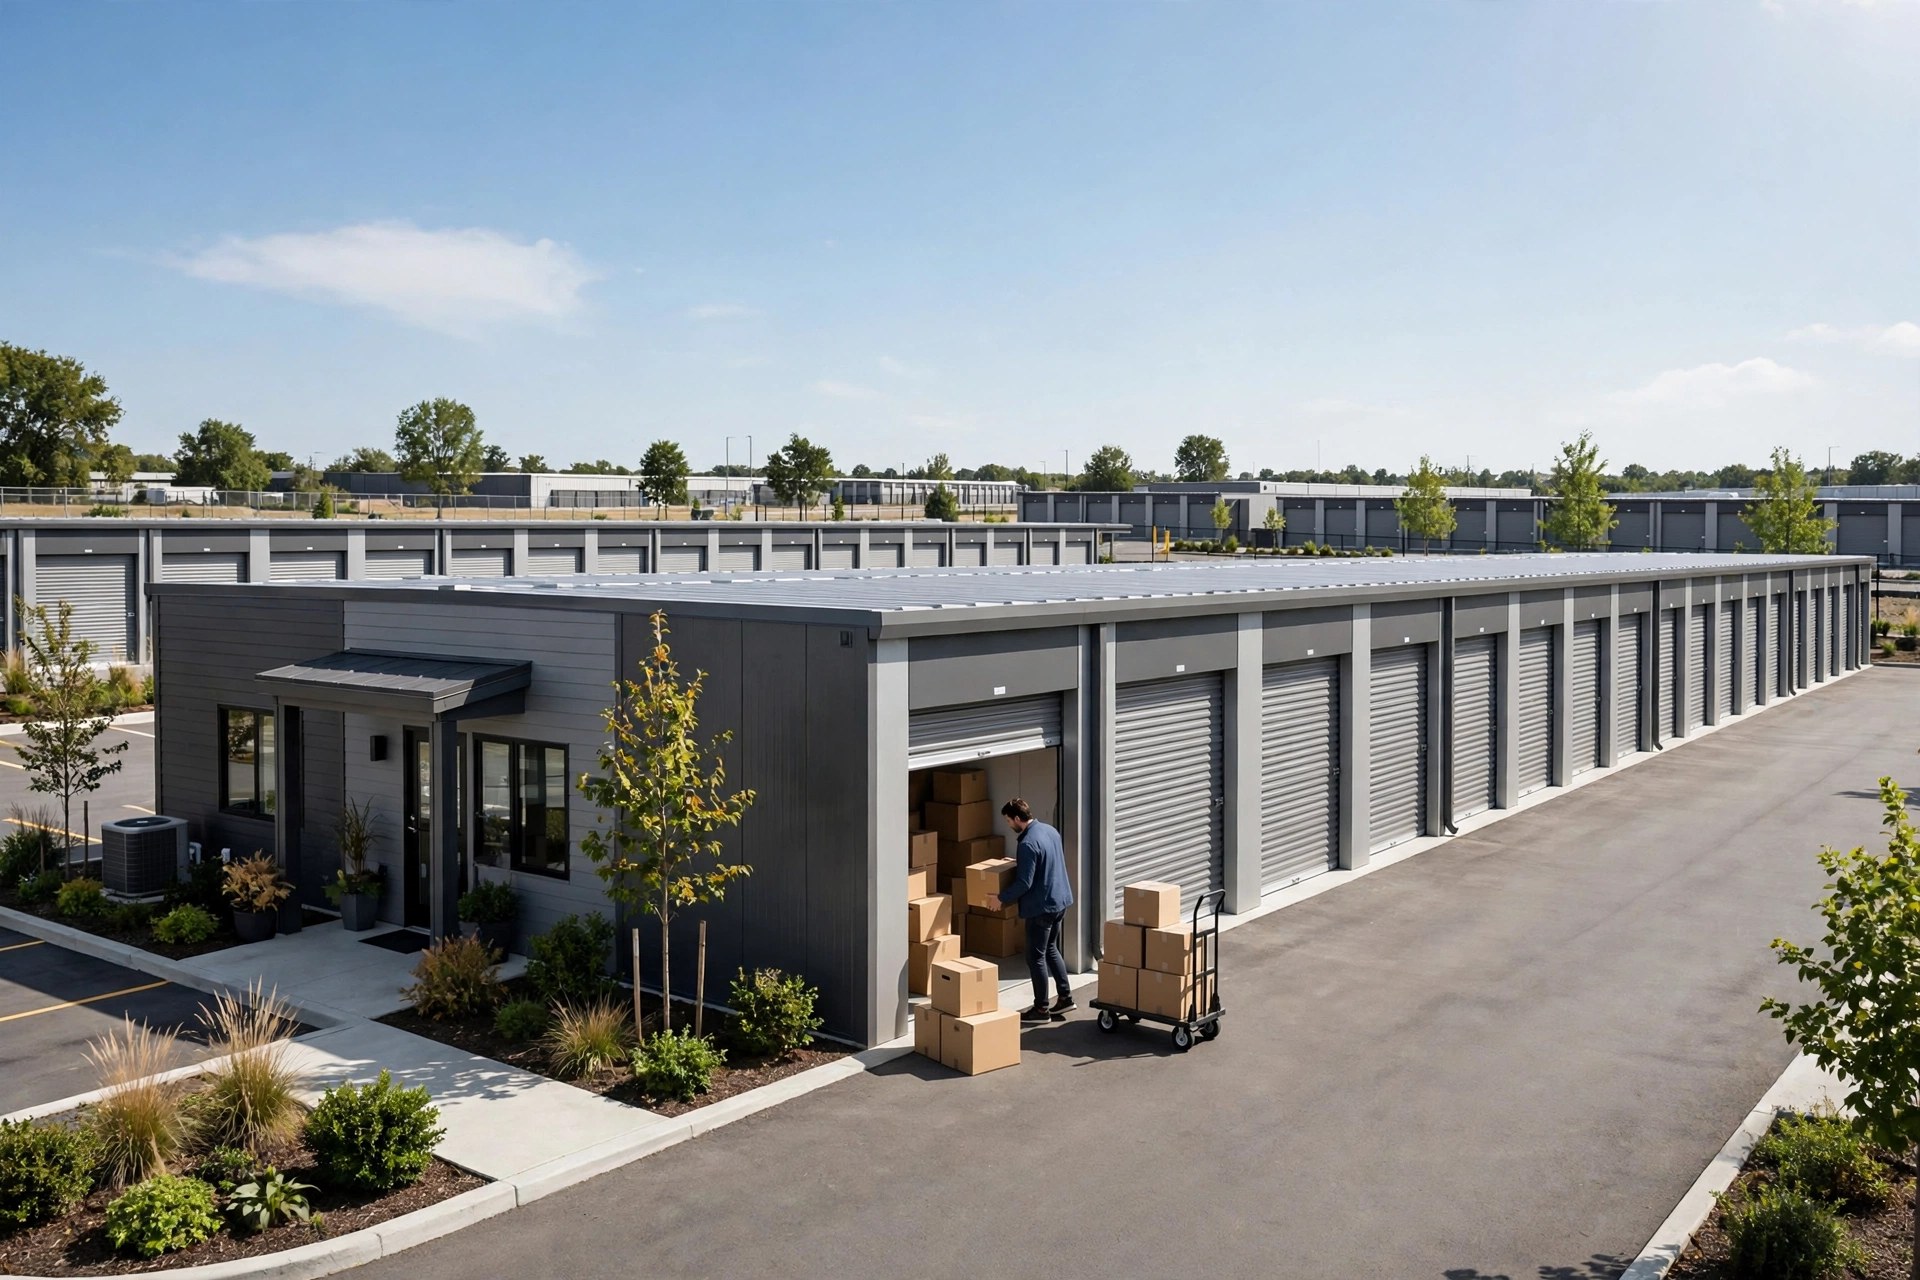
Self-storage facilities do not have a cash-flow problem. They have a timing problem layered on top of a construction problem. A new facility — land, site work, steel buildings, gates, security, and climate-control systems — can cost millions before the first unit rents, and the revenue arrives in small monthly payments that build slowly as occupancy climbs. Meanwhile the mortgage, taxes, insurance, and payroll are due on the same day every month from day one. That is the gap self-storage funding exists to close.
This guide covers how self-storage businesses actually borrow: the five cash demands that recur in nearly every facility, which product fits each one, what lenders check on a storage file, and the five mistakes that turn a good lease-up into a scramble.
Why self-storage borrows on a different calendar
Most businesses sell a product and get paid the same day. A storage facility sells occupancy and gets paid in monthly increments: a unit rented this month pays this month, and the next unit pays next month. The lease-up curve is the whole story — a facility that opens at 20 percent occupancy and climbs to 85 percent over two years is carrying a full mortgage on a fifth of its revenue for the first year. The cost side does not wait for the occupancy curve. The loan payment is monthly, the property taxes are annual, the gate system runs daily, and a roof leak or gate failure stops move-ins outright.
Demand itself is event-driven, not seasonal in the retail sense. Moves, divorces, downsizing, deployments, renovations, and business inventory overflow create storage demand in every month of the year, but the strongest move-in months still cluster around spring and summer, and the winter trough tests every operator's reserves. A facility that staffs and markets for the spring surge and pays for it out of winter collections is borrowing from itself — usually at the worst possible moment.
Then there is the expansion cliff. Storage is a land-and-steel business: the next phase means site work, buildings, and permitting before the first new unit rents, and a conversion — say, turning an old retail box into climate-controlled units — means build-out, fire suppression, and security before a single move-in. Facilities that plan for that cliff borrow on their schedule. Facilities that do not borrow on the vacancy's schedule, which is always worse.
The five cash demands of a self-storage facility
1. Acquisition, construction, and conversion. Buying a facility, building a new one, or converting a warehouse or retail box into storage is the largest single use of capital in the business, and it arrives before the revenue does. These are lumpy, planned purchases that do not fit monthly cash flow.
2. The lease-up float. A new or expanded facility carries a full loan payment while occupancy climbs from opening to stabilization. Marketing, move-in specials, and staffing during lease-up are costs paid months before the unit base that repays them exists.
3. Climate control, security, and systems. Climate-controlled units need HVAC that runs year-round; every facility needs gates, cameras, access control, and management software. Upgrades are lumpy, and a failed gate or HVAC system costs move-ins immediately.
4. Maintenance, roofs, and paving. Steel buildings, roofs, asphalt, and drainage wear on a schedule the operator does not control. Deferred maintenance shows up as vacancies — customers do not rent a leaking unit — so the repair cannot wait for a convenient quarter.
5. Expansion phases and second sites. A second phase or a second location means land, permitting, and construction before the first new rent check. Growth in storage is growth in upfront capital first and occupancy second.
Need working capital this week?
Apply Now →Free to apply · Soft credit check only · Funding in 24–72 hoursThe product map: what fits which need
There is no single right product for a storage facility. There is a right product per need, and mismatching them is the most expensive mistake in this guide.
A business line of credit fits the lease-up float and the seasonal marketing cycle. Draw when move-in specials and staffing costs are high, repay as occupancy climbs, and the line is there again for the next phase. For facilities with repeating occupancy revenue, this is usually the core working facility, and it is worth opening during a strong season rather than during a crunch.
Revenue-based advances fit a single fast gap with a defined collection event: a gate system that failed on Monday and must be running by Friday, a roof repair that cannot wait for the next quarter, a marketing push for a spring lease-up with signed demand behind it. They fund in 24 to 72 hours from a complete application, which matters when move-ins are stopped. They are a poor fit for permanent, repeating costs, because daily debits do not pause for a slow winter.
Equipment and systems financing fits HVAC, gates, cameras, access-control systems, and moving trucks — assets with a serial number and a resale market. The asset itself secures the loan, which usually means better terms than an unsecured advance, and the payment schedule can match the asset's useful life.
Term loans, commercial mortgages, and SBA-backed loans fit the big, one-time moves: acquiring a facility, building a new one, converting a retail box, or financing a full expansion phase. They take longer — days to weeks for a term loan, longer for SBA and commercial mortgages — so they belong in planning, not in emergencies.
The rule of thumb: match the repayment schedule to the cash event that repays it. Float gets a line. A single gap gets an advance. An asset gets equipment financing. A transformation gets a term loan or a mortgage.
What lenders check on a self-storage file
Storage files are judged on occupancy and unit economics as much as on history. Lenders will look at bank statements — typically the last three months — for deposit consistency, average balances, and overdrafts. But they will also ask what a generic application never captures: physical versus economic occupancy, the unit mix by size and climate control, average rent per occupied unit, move-in and move-out rates, and how much of the revenue is tied to a single commercial tenant.
Three things strengthen a storage file more than anything else. First, an occupancy report: physical occupancy, economic occupancy, and the trend over the last twelve months, not just this month's peak. Second, a unit-mix and rent-roll summary: how many units of each size, what share are climate-controlled, and what the street rate is versus the achieved rate. Third, a clean story on the lease-up curve: how long stabilization took, or is projected to take, so the lender underwrites the trough too.
What weakens a file: street rates presented as achieved rates, a pipeline of promised commercial tenants presented as signed leases, and concentration — one business tenant providing most of the revenue. None of these is fatal on its own. All of them together tell a lender the book is softer than the pitch claims.
Five funding mistakes self-storage operators keep making
1. Funding a permanent cost with a daily-debit advance. A mortgage and payroll are forever. An advance is for a gap. Using one for the other means the debit continues long after the gap closed.
2. Taking the first offer during a breakdown. A failed gate is real pressure, but a rushed advance signed at a high factor rate costs more than the days it saved. Get the repair-or-replace quote, then compare the total repayment in dollars before signing.
3. Presenting pipeline as occupancy. Lenders verify. Unsigned commercial leases discovered during underwriting do more damage than a smaller honest occupancy figure would have.
4. Ignoring the maintenance curve. If every roof in the facility is past its expected life, the funding plan must survive the next leak, not the last one. Price the replacement before it is an emergency.
5. Expanding on operating cash alone. A new phase built from collections will be the first project cut in the winter trough. Fund the build, then let occupancy repay it.
How fast self-storage funding moves
Revenue-based products typically fund in 24 to 72 hours from a complete application, once bank statements are verified. A line of credit takes longer to open — days to a couple of weeks — but once open, draws are immediate. Equipment and systems financing usually closes in days to weeks depending on the asset and the file. Commercial mortgages and SBA-backed loans for acquisitions or construction take the longest and should be started a quarter before the money is needed.
The practical move is to open the line during a strong season, keep it mostly undrawn, and use advances only for defined gaps. That combination — a standing line plus a fast advance for surprises — is how storage operators stop letting the occupancy curve run the company.
The bottom line for self-storage facilities
Self-storage is a good business with a hard calendar: cash out for land, steel, systems, and maintenance, cash in only as monthly occupancy climbs toward stabilization. Funders understand that calendar when the file shows it honestly — occupancy trends, unit mix, rent rolls, and the lease-up curve. Match each need to the product built for it, compare every offer by total repayment in dollars, and open the line before you need it. The gate is not the constraint. The lease-up is.
Frequently asked questions
Can a self-storage facility get a business loan?
Yes. Self-storage facilities qualify for commercial mortgages, lines of credit, revenue-based advances, equipment financing, and SBA-backed loans through third-party funders, based on occupancy, unit mix, rent rolls, bank statements, and the lease-up curve. An occupancy report showing physical and economic occupancy over twelve months is often the strongest part of the file.
What do lenders check for self-storage funding?
Physical and economic occupancy and their twelve-month trend, unit mix by size and climate control, average rent per occupied unit, move-in and move-out rates, commercial-tenant concentration, and bank statement health. A rent roll and an occupancy report strengthen any application.
How fast can a self-storage facility get funded?
Revenue-based products typically fund in 24 to 72 hours from a complete application, once bank statements are verified. Equipment financing takes days to weeks, and SBA-backed loans for acquisitions or build-outs take longer. Commercial mortgages and SBA-backed loans for acquisitions or construction take longer and should be started a quarter before the money is needed.
Is a merchant cash advance good for a self-storage facility?
It can be, for a single fast gap with a defined collection event, such as a gate system that failed on Monday and must be running by Friday or a roof repair that cannot wait for the next quarter. For permanent mortgage or payroll costs, a line of credit or term loan usually fits better, because daily debits do not pause for the winter trough.
What documents does a self-storage facility need to apply?
Recent business bank statements, typically the last three months, are the core requirement. A photo ID and a voided check may be requested as optional verification items, but they are not upfront requirements for getting a quote. An occupancy report and a rent roll help where available.
How much funding can a self-storage facility get?
It depends on revenue, seasonality, and the product: revenue-based advances are usually sized as a multiple of monthly revenue, while lines, equipment loans, and term loans depend on the broader file. Ask for the total repayment in dollars before accepting any offer.
The best offer is the one you compare
Get a no-obligation quote from our #1-ranked lender, Coast to Coast Fast Funding — $5K to $5M, MCA and revenue-based products that fund in 24–72 hours with soft-pull-only applications. We shop 75+ lenders so you can compare the true cost of every offer side by side.Apply Now →Soft credit check · 60-second pre-qualification · (352) 809-3201